How Long Does Builders Risk Insurance Coverage Last?

When undertaking a major construction project or home renovation in Colorado, securing the right policy is only half the battle—you also need to know how long that protection lasts. Whether you are a homeowner building a custom property in Castle Rock or a commercial developer in Denver, Builders Risk Insurance provides essential protection for structures, materials, and equipment during the construction process. Unlike standard property policies, this coverage is strictly temporary.

What Determines the Length of Builders Risk Insurance Coverage?
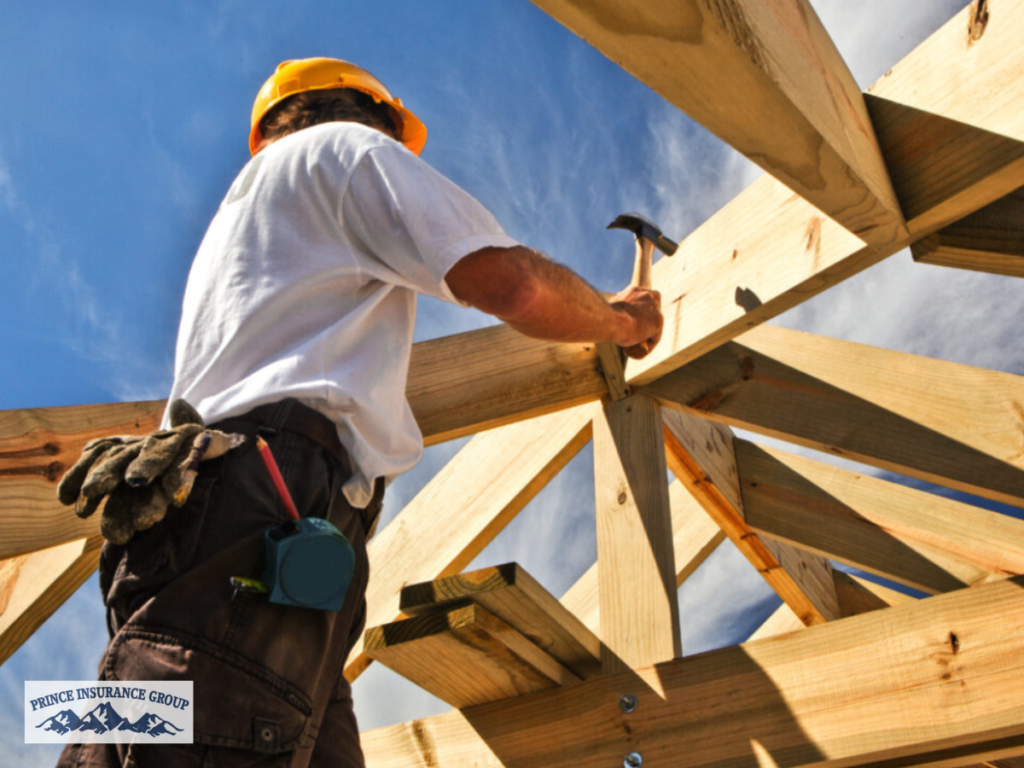
A construction worker building a new wooden structure, representing a project protected by Builders Risk Insurance during the construction process.
How long does your Builders Risk Insurance coverage last? Knowing the key triggers that terminate protection is critical for your project timeline.

The initial term of a Builders Risk Insurance policy is typically written to match your project’s estimated timeline, generally ranging from 6 to 12 months. Policy duration, however, isn’t dictated solely by a specific calendar date. Coverage is designed to terminate upon specific project milestones, ending at whichever event occurs earliest:

  • Policy Expiration Date: The official end date stated in your initial policy schedule.
  • Project Completion or Acceptance: When the owner inspects, accepts, and takes formal ownership of the completed structure.
  • Occupancy or Intended Use: When residents move in, tenants take occupancy, or the building is put to its intended purpose.
  • Transfer of Ownership: When the property is sold, or financial interest in the project officially shifts.

Once a Certificate of Occupancy is issued or permanent property insurance takes over, temporary construction coverage officially ends.

What Happens When a Construction Project Takes Longer Than Expected?

Construction delays are exceptionally common in Colorado. High-altitude weather events like unexpected spring blizzards, late-season hail storms, or municipal permit backlogs can easily push your completion date past schedule.

If your timeline slips, your policy will not automatically renew. Allowing a policy to expire mid-project creates a dangerous gap in protection, leaving theft, structural damage, or severe weather losses completely uninsured.

To avoid losing coverage:

  • Monitor Timelines Proactively: Track your build progress closely against your policy expiration date.
  • Request an Extension Early: Contact your broker well before the policy lapses to secure a extension endorsement. Extensions requested after a policy has expired are subject to fresh underwriting and higher rates.
  • Consider Soft Cost Coverage: Endorsements can protect against the indirect financial impact of delays, such as extended loan interest or municipal re-inspection fees.

Protect your build against unexpected delays and severe weather with tailored coverage solutions designed for local real estate. Contact Prince Insurance today to review your project timeline, secure dynamic Builders Risk Insurance, and safeguard your property from breaking ground to final inspection!

How Often Should I Review My Homeowners Insurance Policy to Ensure Proper Coverage?

home insurance

How Often to Review Your Homeowners Insurance Policy

At Prince Insurance, we recommend reviewing your homeowners insurance policy annually—or immediately following any major life event or structural home modification—to ensure your property remains fully protected against unexpected financial loss. Conducting a comprehensive yearly homeowners insurance review with an experienced insurance broker allows you to adjust your dwelling coverage limits to match rising regional building costs and persistent inflation, keeping your policy aligned with current full replacement values. You should also update your homeowners insurance policy whenever you execute significant home renovations, complete kitchen or bathroom upgrades, build outward additions, or make major purchases like high-value jewelry, electronics, or fine art that require specialized personal property endorsements. Furthermore, key life milestones—such as installing a backyard swimming pool, acquiring a pet, or starting a home-based business—introduce new liability exposures that demand updated liability protection limits or supplemental umbrella coverage. By routinely auditing your policy with Prince Insurance, our independent insurance agents can re-evaluate available carrier discounts, optimize your deductibles, eliminate costly coverage gaps, and deliver a tailored homeowners insurance solution that protects your primary investment and guarantees complete peace of mind.

What Types of Buildings and Property Can Commercial Property Insurance Cover?

Whether you operate a downtown Denver storefront, lease an industrial warehouse in Pueblo, or own an office complex along the Front Range, safeguarding your physical assets is crucial to keeping your enterprise running smoothly. Commercial Property Insurance serves as a foundational safety net, helping Colorado business owners recover financially after unpredictable events like hail, fires, theft, or severe weather.

Which Commercial Buildings, Equipment, Inventory, and Business Assets Can Commercial Property Insurance Protect?

Commercial property building protected by Commercial Property Insurance coverage
Commercial Property Insurance can help protect business buildings, equipment, inventory, and other physical property from covered risks.

A comprehensive policy covers far more than just four walls and a roof. Commercial Property Insurance safeguards a wide array of physical and tangible assets:

  • Real Property & Structures: Owned office buildings, retail storefronts, manufacturing facilities, storage sheds, and detached garages.
  • Tenant Improvements & Alterations: Upgrades made to leased spaces, such as custom flooring, built-in cabinetry, or specialized lighting installed by a tenant.
  • Business Personal Property: Office furniture, fixtures, computers, point-of-sale systems, and specialized machinery or tools.
  • Inventory & Stock: Raw materials, goods currently in production, and finished products stored on-site waiting for distribution or sale.
  • Outdoor Assets: External signage, perimeter fencing, outdoor seating, and landscaping elements directly on your commercial grounds.

How Does Property Insurance Coverage Vary by Property Type and Business Needs?

Coverage isn’t one-size-fits-all; policies adapt dynamically based on your industry, ownership model, and location.

  • Property Owners vs. Tenants: Building owners require broad coverage for structural repair or total replacement. Tenants, on the other hand, typically focus on contents coverage and tenant improvements rather than insuring the landlord’s physical building structure.
  • Valuation Methods: Policies pay claims based on either Actual Cash Value (replacement cost minus depreciation) or Replacement Cost Coverage (reimbursement for new replacement items without deducting for age).
  • Regional & Industry Endorsements: Colorado businesses face severe weather risks like high-altitude windstorms and major hail. A high-risk facility, seasonal retail shop, or restaurant may require specialized endorsements—such as Equipment Breakdown, Spoilage, or Business Interruption coverage—to bridge standard policy gaps during mandatory closures.

Don’t wait for an unexpected disaster or storm season to reveal gaps in your coverage. Consult with Prince Insurance today to get a customized quote for Commercial Property Insurance and secure total peace of mind for your business!

Do I Need Specialized Sports Bar Insurance If I Already Have Restaurant Coverage?

sports bar insurance

Why Standard Restaurant Coverage Isn’t Enough: The Case for Specialized Sports Bar Insurance

At Prince Insurance, we strongly advise that standard restaurant coverage is rarely sufficient to handle the unique, high-energy risks of running a sports venue, making specialized sports bar insurance an essential protection for your business. While standard commercial food service policies cover basic general liability and property loss, a custom sports bar insurance package directly addresses elevated operational hazards—such as packed game-day crowds, extended late-night hours, and high alcohol sales volumes. Securing tailored sports bar insurance ensures your venue is backed by robust liquor liability coverage, crucial assault and battery protection for potential crowd altercations, and high-limit commercial property coverage for expensive multi-screen audio/visual setups and specialized tap systems. Furthermore, a comprehensive sports bar insurance plan shields your financial stability against slip-and-fall claims, cyber threats to modern point-of-sale systems, and sudden business interruption during major playoff seasons. By partnering with Prince Insurance to secure targeted sports bar insurance, owners can confidently protect their high-value entertainment assets, mitigate industry-specific liabilities, and keep their doors open for every kickoff.

Why Is Tree Care Insurance Important for Colorado Tree Service Businesses?

Operating a tree service business in Colorado comes with unique rewards and serious risks. From high-altitude windstorms and heavy snowfall to unpredictable mountain terrain, tree care professionals routinely face hazardous working conditions. Whether you are managing a small local crew or running a large commercial outfit, securing comprehensive Tree Care Insurance is crucial for protecting your livelihood, your employees, and your clients.

How Tree Care Insurance Helps Protect Colorado Businesses From Property Damage and Liability Claims

Tree service professional working safely on a tree while Tree Care Insurance helps protect a Colorado tree care business
Tree Care Insurance can help Colorado tree service businesses manage risks associated with tree removal, trimming, equipment, and property damage.

Tree trimming, pruning, and removal pose inherent risk. A single falling branch can crack a roof, smash a vehicle, or tear down power lines. If an unexpected accident occurs on a job site, liability claims can quickly jeopardize your company’s financial future. Comprehensive Tree Care Insurance provides vital general liability coverage that pays for property repairs and third-party medical costs, preventing out-of-pocket expenses from draining your operational capital. Having proper liability protection builds trust with potential customers, reassuring homeowners and property managers across Colorado that your business is legitimate, reliable, and responsible.

What Coverage Should Tree Service Businesses Consider for Employees, Equipment, and Job-Site Risks?

Because tree care involves dangerous machinery and high-elevation work, a basic plan is rarely enough. A well-rounded policy tailored for Colorado tree services should include key coverages:

  • Workers’ Compensation: Essential for covering medical bills and lost wages if an employee is injured by falling debris, chainsaw mishaps, or heat exhaustion.
  • Commercial Auto & Mobile Equipment (Inland Marine): Protects specialized machinery—such as wood chippers, bucket trucks, and stump grinders—whether in transit or stored at a job site.
  • Job-Site Risk & Environmental Coverage: Safeguards your business against specialized hazards, including chemical overspray or accidental utility line disruption during excavations and tree removals.

Tailoring your insurance package to match Colorado’s specific weather hazards and high-elevation risks ensures your business remains fully compliant, competitive, and resilient against unexpected losses.

Don’t leave your business exposed to costly claims or equipment losses. Contact our local insurance experts today for a customized quote on Tree Care Insurance and secure peace of mind for your team and clients!

What’s The Difference Between Artisan Contractor Insurance and General Contractor Insurance?

artisan contractor insurance

The Difference Between Artisan Contractor Insurance and General Contractor Insurance

At Prince Insurance, we understand that selecting the right commercial coverage hinges on recognizing how specialized trades differ from broad project management—which is precisely where the distinction between artisan contractor insurance and general contractor insurance lies. While general contractor coverage is designed for oversight professionals managing multi-phase, large-scale job sites with extensive subcontractor exposure, artisan contractor insurance provides tailored liability protection engineered specifically for trade-specific craftsmen, such as electricians, plumbers, carpenters, and painters. A comprehensive artisan contractor insurance policy focuses on the unique operational risks, high-skill hand tool usage, and direct physical work associated with a single specialty, offering flexible policy structures, tailored tools and equipment floaters, and specialized contractor general liability coverage without forcing trade specialists to pay for the high-risk, broad-scope exposures inherent to general contracting. By partnering with Prince Insurance to secure targeted artisan contractor insurance, trade professionals receive cost-effective risk management, precise property damage and bodily injury protection, and the official certificates of insurance necessary to land commercial contracts and safeguard their business bottom line.

What Types of Risks Make Excavation Contractor Insurance Necessary for Contractors?

Equipment Insurance protecting heavy equipment used for business operations.

Excavation is the foundational first step for many of Colorado’s most exciting building projects, but moving earth is inherently unpredictable. From the shifting soils of the Front Range to the rocky terrain of the Rockies, digging operations face severe structural and financial threats every day. For local business owners, securing comprehensive Excavation Contractor Insurance isn’t just a regulatory formality—it is a critical shield against devastating financial liabilities.

What Job Site Hazards and Ground Conditions Increase the Need for Excavation Contractor Insurance?

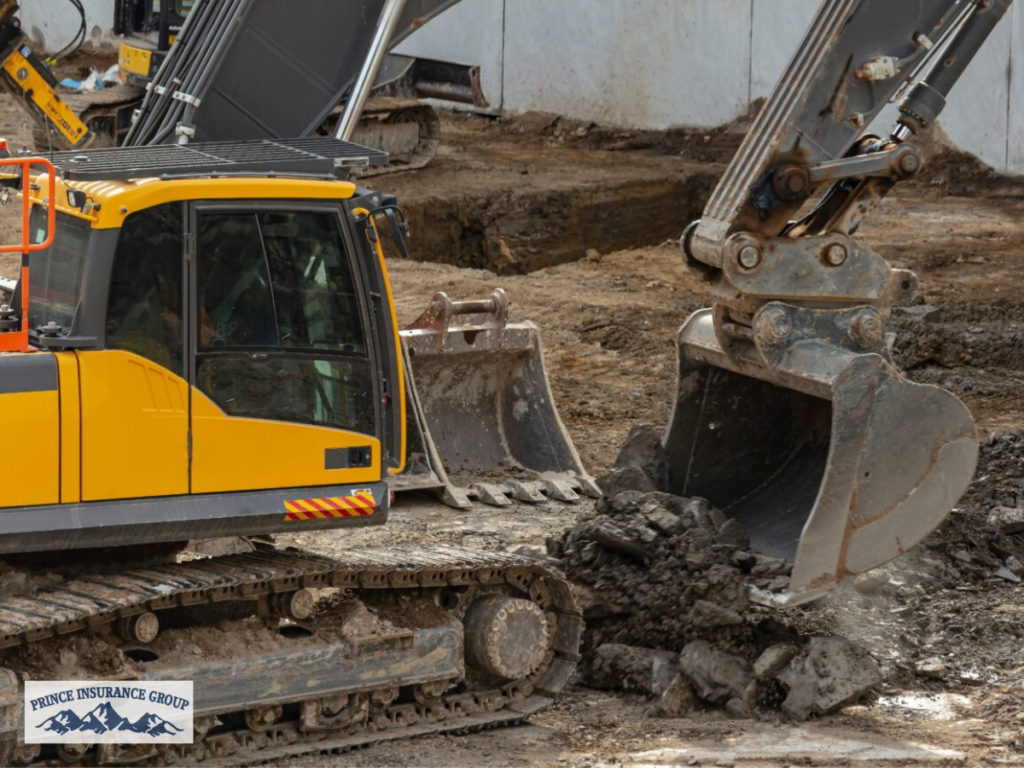
Excavators working at an active construction site, highlighting the importance of Excavation Contractor Insurance for protecting heavy equipment and excavation operations.
Excavation Contractor Insurance helps protect contractors from common risks such as equipment damage, third-party liability, workplace injuries, and unexpected project delays.

No two dig sites in Colorado are exactly alike, and the natural environment introduces massive operational uncertainties that make Excavation Contractor Insurance a necessity. One of the most severe hazards is a trench collapse or cave-in, which can trap workers and heavily damage expensive machinery. Ground conditions play a major role in these risks; Colorado’s notorious expansive clay soils swell and shrink rapidly with weather changes, compromising trench stability. Hitting unexpected underground water tables or navigating hidden boulders can cause heavy equipment to overturn or fail, resulting in thousands of dollars in project delays and repair costs.

How Do Property Damage and Third-Party Liability Risks Impact the Need for Insurance?

Beyond natural ground hazards, excavation work takes place in close proximity to existing public and private infrastructure, driving home the need for Excavation Contractor Insurance. Even with careful utility mapping, accidental strikes on underground power lines, gas mains, or fiber-optic cables occur frequently. Such incidents can disrupt service to entire neighborhoods, triggering immense property damage claims and steep municipal fines. Excavation sites naturally attract third-party liability risks, making robust Excavation Contractor Insurance essential for protecting your business. Passersby or visitors can easily suffer injuries from falling into open pits, tripping over construction debris, or being struck by displaced rocks, leaving your business highly vulnerable to costly medical bills and legal defense fees.

Protect your hard work and your company’s future from the unpredictable elements of the job site. Whether you are navigating complex commercial liabilities or searching for tailored personal policy options, our local team is here to help. Contact Prince Insurance to get a customized quote and ensure your business has the robust protection it deserves!

What Coverage Should I Look for In Condo Association Insurance for HOA Properties?

Secure Your Community Infrastructure with Authoritative Condo Association Insurance

At Prince Insurance, we provide sophisticated risk management advisory services to community boards, advising that structuring an authoritative condo association insurance program requires a meticulous evaluation of property boundaries, governance liabilities, and systemic operational exposures. As an industry-leading commercial insurance broker, we emphasize that the foundation of any robust condo association insurance policy rests on its structural property framework, which must be clearly defined as either a “bare walls” policy covering only the building’s shell and common elements, or a comprehensive “all-in” or single-entity master policy that extends coverage to original interior unit fixtures like cabinetry, flooring, and appliances. Beyond the physical structures, a high-tier condo association insurance package must feature substantial commercial general liability limits to absorb legal defense costs from common-area slip-and-falls, robust Directors and Officers (D&O) liability insurance to defend board members against governance or fiduciary lawsuits, and strict fidelity or crime coverage to protect association reserves from internal theft or fraud. Partnering with the dedicated community association risk specialists at Prince Insurance ensures your HOA implements a highly compliant, expertly tailored condo association insurance portfolio that seamlessly addresses volatile building replacement costs, optimizes loss assessment structures, and legally fortifies the collective financial assets of your community.

What Are Common Claims Filed Under Sports Bar Insurance Policies?

Picture this: It’s a packed weekend night, a Colorado home team just scored a thrilling victory, and your establishment is absolutely electric. While this high-energy atmosphere is exactly what makes running a local venue so rewarding, it also creates a perfect storm for unexpected accidents. From rowdy celebrations to sudden spills, navigating these unique risks requires a clear understanding of Sports Bar Insurance and the common claims that could otherwise sideline your hard-earned business.

What Types of Liability Claims Are Most Common Under Sports Bar Insurance Policies?

Busy sports bar filled with customers, highlighting the need for Sports Bar Insurance coverage to protect against common business risks and claims.
Sports Bar Insurance helps protect sports bar owners from potential claims involving property damage, customer injuries, liquor liability, and other business-related risks.

Liability risks are a primary concern for any hospitality owner. Slippery floors from spilled beers, dim lighting during evening games, and tightly packed tables can easily lead to slip-and-fall accidents. These general sports bar insurance claims can cost thousands of dollars in medical bills and legal fees if a patron gets injured on your property.

Property damage claims are also highly frequent. When game-day emotions run high, accidental or intentional damage to high-end television screens, audio equipment, or building structures can occur. Whether it is an unruly fan reacting to a missed field goal or a sudden kitchen fire breaking out during halftime prep, comprehensive physical damage coverage within your policy ensures your business recovers quickly without devastating out-of-pocket costs.

How Do Alcohol-Related Incidents and Employee Claims Impact Bar Insurance?

As a sports bar owner, alcohol service is central to your revenue, but it also presents your greatest exposure. Under Colorado’s strict dram shop laws, your business can be held legally liable if you serve a visibly intoxicated patron who subsequently causes an auto accident or harms someone else. Liquor liability insurance is a critical shield against these potentially catastrophic claims, covering legal defense fees and settlements arising from alcohol-related altercations or accidents.

Internal risks involving your staff cannot be overlooked. Busy game nights mean fast-paced environments where kitchen staff face burn risks and servers can experience repetitive strain or slip injuries. Workers’ compensation claims protect your employees while shielding your business from direct lawsuits, ensuring a safe and legally compliant workplace.

Navigating the complexities of commercial liability requires a partner who understands the unique landscape of Centennial State businesses. Whether you are seeking robust Sports Bar Insurance to protect your commercial establishment or looking to bundle your coverage with tailored personal insurance policies, our experienced local agents are here to help. Contact Prince Insurance today to secure a comprehensive insurance strategy designed to safeguard your business, your family, and your peace of mind.

How Does Cyber Liability Insurance Protect My Business from Data Breaches and Online Threats?

artisan contractor insurance

Protect Corporate Assets and Financial Stability with Comprehensive Cyber Liability Insurance

At Prince Insurance, we provide comprehensive risk management solutions designed to safeguard your corporate assets, recognizing that a robust cyber liability insurance policy serves as your business’s ultimate financial defense against devastating data breaches, ransomware attacks, and evolving online threats. As an authoritative, full-service commercial insurance broker, we specialize in structuring tailored cyber liability insurance programs that seamlessly integrate first-party and third-party protections to mitigate both immediate operational costs and long-term liability exposures. Through first-party coverage, our custom cyber liability insurance policies immediately absorb the crushing financial impact of an active network intrusion by funding deep digital forensic investigations, legal counsel for regulatory compliance, mandatory customer notification services, and specialized PR crisis management, while also replacing lost income driven by network business interruptions. Concurrently, the third-party provisions of our premier cyber liability insurance deliver vital defense mechanisms, covering steep legal defense fees, regulatory fines, and court-approved class-action settlements if clients, vendors, or regulatory bodies sue your organization for failing to secure their sensitive, personally identifiable information (PII). Partnering with the dedicated commercial risk specialists at Prince Insurance ensures your enterprise secures a high-tier, fully compliant cyber liability insurance framework that satisfies rigorous underwriter control maturity guidelines, patches critical security coverage gaps, and guarantees the enduring stability of your digital infrastructure in a highly volatile global threat landscape.