What Does Auto Insurance Typically Cover for Your Vehicle?

Driving in Colorado is as beautiful as it is unpredictable. From navigating sudden seasonal hailstorms on the Eastern Plains to maneuvering through heavy winter snow on a weekend trek up to Vail, our vehicles take a beating. For local drivers and business owners alike, maintaining the right Auto Insurance is about far more than just keeping a valid registration card in the glovebox. It is your financial shield against the unique road hazards of the Centennial State, making it essential to know exactly what your policy protects—and what it leaves out.

Understanding the Different Types of Auto Insurance Coverage
Driver holding a steering wheel inside a vehicle, representing Auto Insurance coverage that helps protect drivers, passengers, and vehicles on the road.
Understanding what your Auto Insurance covers can help you choose the right protection for your vehicle, passengers, and financial security.

A standard Auto Insurance policy isn’t just a single blanket of protection; it is made up of several distinct coverage types designed for different scenarios:

  • Liability Coverage: This is mandatory in Colorado. It pays for bodily injury and property damage you cause to others in an accident, though it does not cover your own vehicle’s damages.
  • Collision Coverage: This pays to repair or replace your vehicle if you’re involved in an accident with another car or a fixed object (like a guardrail), regardless of who is at fault.
  • Comprehensive Coverage: Essential for Colorado’s unpredictable environment, this covers damage to your vehicle caused by events outside your control, such as hail storms, wildlife collisions (like hitting an elk), theft, or vandalism.
  • Medical Payments (MedPay): Colorado insurance companies must offer you MedPay, which helps cover medical expenses for you and your passengers after an accident, no matter who caused it.

Common Exclusions and Limitations in Car Insurance Policies

While Auto Insurance offers robust financial safety nets, it doesn’t cover everything. Being aware of policy exclusions prevents costly surprises down the road:

  • Wear and Tear: Standard policies do not pay for routine maintenance, mechanical breakdowns, electrical failures, or bald tires.
  • Commercial Use: If you use your personal vehicle for business deliveries or ridesharing without a commercial endorsement, your insurer will likely deny claims arising during those activities.
  • Personal Belongings: If your laptop or tools are stolen from your vehicle, your car insurance generally won’t cover them—that typically falls under homeowners or business property insurance.

Every driver and business owner has unique risk factors, especially when dealing with Colorado’s diverse terrain and weather. Don’t wait until you’re stranded on the side of the road to find out if you have the right protection. Consult with Prince Insurance today to get a personalized Auto Insurance quote and ensure you are fully covered for the road ahead.

What Is Included in Arborists / Tree Care Insurance, and Does It Cover Climbing Accidents?

tree care insurance

Comprehensive Arborists & Tree Care Insurance for High-Risk Operations

At Prince Insurance, we provide specialized arborists care insurance and comprehensive tree care insurance packages specifically engineered to protect tree service contractors from the extreme, high-liability risks inherent to the tree trimming and removal industry. A robust, enterprise-grade tree service insurance policy includes general liability to cover catastrophic third-party property damage—such as a falling limb striking a client’s home—paired with commercial auto insurance for your specialized fleet of bucket trucks and chip trucks. Crucially, regarding high-risk climbing accidents and ground-crew injuries, standard liability does not apply; instead, our specialized tree trimmer insurance programs explicitly incorporate robust workers’ compensation insurance to cover medical expenses, rehabilitation costs, and lost wages for employees injured while working at extreme heights. As a premier commercial insurance agency, we also weave essential inland marine coverage into your tree care insurance policy to safeguard expensive rigging, chainsaws, and stump grinders against theft or damage, alongside professional liability to protect your certified consulting arborist staff. By partnering with an expert insurance broker to tailor your tree care business insurance, you can secure competitive arborists care insurance quotes that deliver airtight risk mitigation, ensure absolute compliance with local municipal contracts, and completely shield your company’s financial future.

How Often Should You Review and Update Your Business Insurance Policy?

Running a business in Colorado is an adventure as dynamic as our weather. Whether you are navigating the booming tech scene in Denver, managing a boutique in Fort Collins, or running a seasonal venture in the Rockies, change is your only constant. Amidst managing supply chains and hiring staff, there is one critical asset protection step that often gets overlooked: evaluating your Business Insurance. While a standard annual check-up is a great baseline, your coverage should never hit autopilot in a fast-growing economy.

Key Business Changes That Require an Insurance Policy Review

Business Insurance policy document with a magnifying glass and eyeglasses on a desk, symbolizing the importance of reviewing and updating insurance coverage regularly.
Regularly reviewing your Business Insurance policy helps ensure your coverage keeps pace with business growth, operational changes, and emerging risks.

While an annual check-up is an excellent rule of thumb, major organizational milestones should trigger an immediate review of your Business Insurance. Failing to update your policy during times of change can leave you dangerously underinsured or paying for coverage you no longer need.

  • Growth and Expansion: If you’ve opened a new storefront in Colorado Springs, expanded your office space, or increased your workforce, your liability and property risks have shifted.
  • Asset Purchases: Investing in heavy machinery, a new commercial vehicle fleet, or upgrading your specialized IT infrastructure means you have more physical value to protect.
  • Operational Shifts: Pivoting your business model—such as a local restaurant introducing a dedicated delivery service or a retailer transitioning completely to e-commerce—introduces entirely new risk vectors, like commercial auto liability or cyber threats.

Tips for Staying Proactively Updated on Your Business Insurance

You don’t have to wait for an emergency or your annual renewal date to ensure your coverage aligns with your operations. Staying proactive keeps your business resilient.

  • Schedule Regular Milestones: Mark your calendar for a mid-year check-in specifically dedicated to operational risk assessments.
  • Maintain an Asset Inventory: Keep a live, updated log of all equipment, technology, and real estate changes so it’s readily accessible when you speak to an expert.
  • Foster an Open Dialogue: Establish a strong partnership with a local insurance professional who understands the unique regulatory and environmental factors affecting Colorado businesses.

Protecting your enterprise means ensuring your coverage evolves alongside your vision. Don’t wait until a claim arises to discover gaps in your protection. Contact Prince Insurance today for a comprehensive Business Insurance review and let us help you safeguard your future.

How Does Towing Insurance Work for Roadside Assistance and Tow Truck Companies?

Towing truck assisting a disabled vehicle on roadside, illustrating reliable Towing Insurance coverage for compliant and protected towing businesses.

Comprehensive Towing Insurance for Roadside Assistance Fleets

At Prince Insurance, we provide specialized commercial towing insurance solutions engineered to protect roadside assistance providers and tow truck operators from the unique, high-liability risks they face every single day on the road. A robust, enterprise-grade tow truck insurance policy operates through a strategic combination of critical coverage layers, starting with commercial auto liability to cover bodily injury and property damage during transit, paired with essential on-hook towing insurance to protect the customer vehicles currently attached to your hoist or flatbed. As a premier commercial insurance agency, we ensure your business is fully shielded by incorporating garagekeepers liability insurance to safeguard client vehicles while they are stored at your service facility, alongside comprehensive commercial auto insurance to cover your own fleet against physical damage from collisions, theft, or vandalism. By partnering with an expert insurance broker to customize your tow truck liability insurance, you can secure competitive towing insurance quotes that perfectly balance robust risk mitigation with operational affordability. This comprehensive approach ensures that whether your fleet is executing a complex recovery or providing routine emergency roadside assistance, your business assets, employees, and customer property remain entirely protected under an airtight commercial policy.

What Liability Protection Does Homeowners Insurance Provide?

Homeowners Liability insurance protection covering accidents, property damage, and common claims filed by Colorado homeowners.

When most residents in the Centennial State think about Homeowners Insurance, they picture protection for their physical property—shielding their mountain cabin from wildfire or their suburban roof from a sudden Front Range hailstorm. While dwelling coverage is vital, there is another, often overlooked component that is equally critical to your financial survival: personal liability protection. In an increasingly litigious world, this portion of your policy acts as a legal and financial shield, protecting your life savings if you are found legally responsible for injury or property damage to others.

Personal Homeowners Insurance Liability Coverage Explained

Residential home exterior representing Homeowners Insurance coverage, highlighting property protection, liability coverage, and financial security for homeowners. Homeowners Associations (HOA) Insurance
Homeowners Insurance provides essential liability protection, helping homeowners manage risks from accidents, injuries, and property-related claims.

At its core, the liability portion of your Homeowners Insurance is designed to pay for two main things: the damages you owe to another person and the legal fees required to defend you. In Colorado, where social gatherings and outdoor hospitality are a way of life, this coverage is essential.

Imagine a guest trips on an uneven patio stone during a backyard barbecue and suffers a serious injury. Without liability coverage, you could be personally responsible for their medical bills, lost wages, and pain and suffering. Personal liability coverage typically starts at $100,000, though many Colorado agents recommend increasing this to $300,000 or $500,000, given the rising costs of healthcare and legal representation. This coverage doesn’t just apply to “slip and fall” accidents; it also covers damage your pets might cause, such as a dog bite, which is a significant consideration for the many dog-loving households across the state.

When Liability Protection Applies Beyond Your Home

One of the most surprising features of Homeowners Insurance is that the liability protection is “worldwide.” It follows you and the family members living in your household wherever you go, not just within the boundaries of your property.

  • Travel Incidents: If you are vacationing in Aspen and accidentally collide with another skier, causing them injury, your home policy’s liability coverage can step in to handle the claim.
  • Property Damage: If you are shopping in a boutique in Boulder and accidentally knock over an expensive display, your insurance can cover the replacement costs.
  • Defamation and Slander: Many modern policies include (or allow you to add) protection against “personal injury” claims, which include libel or slander, providing a safety net in the age of digital communication.

Your home is your sanctuary, but your insurance should be your fortress. Understanding that your policy protects your assets both inside and outside your property line is the first step toward true peace of mind. Get your personalized coverage review with Prince Insurance and ensure that you, your family, and your future are fully protected!

What Does Restaurant Insurance Cover, and How Can It Protect My Food Service Business?

A busy bar in Colorado, highlighting the importance of bar insurance for liquor liability protection and legal compliance.

Comprehensive Restaurant Insurance Coverage: Expert Risk Mitigation for Your Food Service Business

At Prince Insurance, we recognize that a robust restaurant insurance policy is the cornerstone of a resilient food service business, providing a multifaceted safety net against industry-specific risks. A high-quality commercial insurance package for eateries must include general liability insurance to defend against common third-party claims like slip-and-fall accidents and foodborne illness allegations. To secure your physical assets, commercial property insurance is vital for protecting high-value kitchen equipment, inventory, and signage from kitchen fires, theft, and natural disasters. Furthermore, we emphasize the inclusion of liquor liability insurance for establishments serving alcohol to mitigate risks associated with intoxicated patrons, alongside food spoilage and contamination coverage to reimburse losses from power outages or equipment failure. Beyond physical assets, workers’ compensation insurance is essential for covering employee injuries, while business interruption insurance ensures financial stability by replacing lost income during forced closures. By partnering with a specialized insurance broker to tailor your business owners policy (BOP), you can integrate product liability, equipment breakdown, and cyber liability into a seamless insurance portfolio that optimizes your policy limits and safeguards your long-term profitability.

What Risks Does Cannabis Insurance Help Mitigate in Colorado?

Colorado has long been a pioneer in the legal cannabis industry, fostering a market that ranges from boutique dispensaries in Denver to large-scale cultivation facilities in Pueblo. Being a trailblazer, however, comes with a unique set of hazards. Despite state legality, the cannabis industry operates in a complex gray area regarding federal law, banking, and traditional risk management. For business owners in the Centennial State, Cannabis Insurance is not just an optional safeguard—it is a foundational necessity designed to mitigate the high-stakes risks inherent in this specialized sector.

Protecting Against Property Damage and Theft with Cannabis Insurance

Legal cannabis cultivation facility in Colorado representing Cannabis Insurance coverage for property, liability, and business risk protection in the industry.
Cannabis Insurance helps Colorado cannabis businesses manage risks such as theft, property damage, and liability while ensuring regulatory compliance and stability.

Cannabis businesses are often targets for specialized criminal activity due to the high value of the product and the cash-heavy nature of the transactions. Standard commercial policies often contain “Schedule 1” exclusions that can leave a business owner high and dry after a loss.

Dedicated Cannabis Insurance provides targeted protection for physical assets. This includes “Crop Coverage,” which protects the living plants against equipment failure, fire, or localized natural disasters like the sudden hailstorms common on the Front Range. Specialized theft coverage also accounts for both finished inventory and the cash held on-premises. Because cannabis products require specific environmental controls, many policies also include Spoilage Coverage, ensuring that if a climate-control system fails in a warehouse, the resulting financial loss doesn’t bankrupt the operation.

Managing Liability and Regulatory Risks

Beyond physical property, the greatest threat to a Colorado cannabis business often comes from legal and regulatory challenges. In a highly regulated environment, a single compliance oversight or a product-related illness can lead to license revocation or multi-million dollar lawsuits.

  • Product Liability: As consumer patterns shift toward concentrates and edibles, the risk of a product-related injury claim increases. This insurance protects the business if a consumer alleges a product was contaminated or incorrectly labeled.
  • General and Professional Liability: Just like any other retail or manufacturing space, dispensaries face risks from “slip and fall” accidents. They also face unique professional liability risks regarding the advice given by budtenders to customers.
  • Regulatory Defense: Colorado’s Marijuana Enforcement Division (MED) maintains strict standards. Some Cannabis Insurance packages offer coverage for legal expenses incurred during regulatory audits or administrative hearings, providing a vital safety net for maintaining your operational license.

The cannabis industry is a cornerstone of the modern Colorado economy, but it remains one of the most volatile sectors to navigate. Protecting your hard work requires a partner who understands the specific nuances of state law and industry-specific risks. Contact Prince Insurance today for a tailored risk assessment.

How Do I Choose the Right Equipment Insurance for My Tools and Machinery?

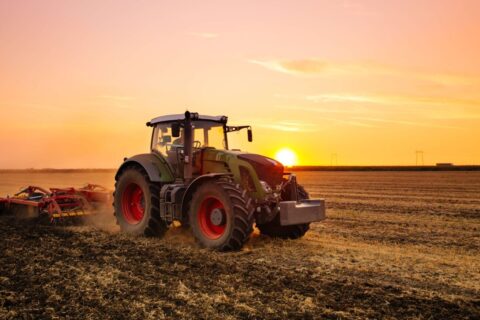
Farm Equipment Insurance coverage shown with a tractor operating on a barley field at sunset, illustrating protection for essential farming machinery.

Strategic Equipment Insurance Solutions: Protecting Your Tools and Machinery with Prince Insurance

At Prince Insurance, we recommend a comprehensive approach that begins with a precise valuation of assets, ensuring you distinguish between replacement cost coverage—which provides for new equipment without depreciation—and actual cash value (ACV). To effectively mitigate risk, businesses must secure inland marine insurance (often referred to as an equipment floater) to protect mobile tools and machinery while in transit or at various job sites, as standard commercial property insurance typically only covers items at a fixed location. Furthermore, high-authority protection requires integrating equipment breakdown coverage to shield against internal perils like mechanical failure, electrical surges, and motor burnout, which are standard exclusions in basic general liability or business owners policies (BOP). For specialized industries, we emphasize the importance of scheduled equipment listings for high-value machinery to ensure full indemnity in the event of theft or accidental damage. By partnering with an expert insurance broker to tailor your commercial insurance portfolio, you can optimize your deductibles and policy limits, effectively transforming your business insurance from a mandatory expense into a robust asset-protection strategy.

When Should a Contractor Consider Sub-Contractor Insurance Coverage?

sub-contractor insurance

Protecting Your Business: The Essential Role of Sub-Contractor Insurance in Risk Management

At Prince Insurance, we advise that a general contractor must prioritize sub-contractor insurance the moment they delegate any portion of a project to a third-party trade, as this coverage is the primary line of defense against vicarious liability and catastrophic financial loss. Implementing rigorous sub-contractor insurance requirements ensures that if a hired plumber, electrician, or framer causes bodily injury or property damage on the job site, the primary contractor’s own master policy remains insulated from the claim. Our authoritative approach to sub-contractor insurance emphasizes the necessity of verifying high-limit general liability and workers’ compensation through comprehensive certificates of insurance (COI) before any work commences. Furthermore, securing specific sub-contractor insurance endorsements, such as “additional insured” status, is a critical strategic move that shifts the legal and financial burden of a mishap onto the sub-contractor’s carrier, thereby protecting the general contractor’s loss history and long-term insurability. By maintaining a strict protocol for sub-contractor insurance, construction firms mitigate the risks of “completed operations” claims and ensure that their profit margins aren’t eroded by legal fees or damages caused by the negligence of others. Ultimately, Prince Insurance views sub-contractor insurance as a non-negotiable risk management tool that provides the structural integrity needed to scale a construction business safely while maintaining the trust of developers and high-value project stakeholders.

How Do You Choose the Right Artisan Contractor Insurance for Your Trade?

In Colorado’s thriving construction and home improvement market, “Artisan Contractors”—the skilled electricians, plumbers, carpenters, and painters who build our communities—face a unique set of risks. From navigating icy job sites in Aspen to managing residential renovations in the Denver suburbs, your hands-on expertise is your livelihood. One accidental slip or faulty installation, however, can lead to costly litigation that threatens your business. Selecting the right Artisan Contractor Insurance is not just a regulatory requirement; it is a strategic move to protect your reputation and your financial future.

Evaluating Artisan Contractor Insurance Coverage Needs Based on Your Trade

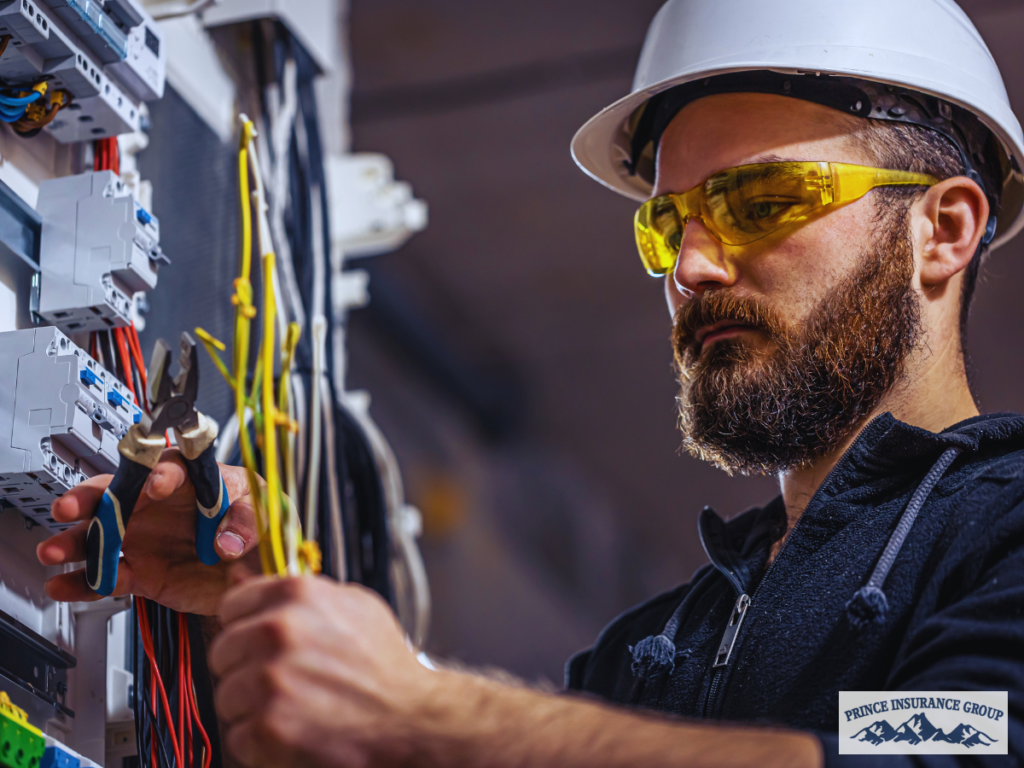
Electrician working on wiring at a job site, illustrating Artisan Contractor Insurance coverage for protecting skilled trades, tools, and work-related risks.
Artisan Contractor Insurance helps safeguard tradespeople by covering job site risks, tools, and liabilities while supporting reliable and compliant operations.

The term “artisan” covers a broad spectrum of skills, and your insurance policy should be as specialized as your toolkit. A general, one-size-fits-all policy often leaves dangerous gaps in coverage.

For example, a plumber requires robust “completed operations” coverage to protect against water damage claims that might arise months after a job is finished. A high-end carpenter or cabinet maker might prioritize “inland marine” coverage to protect expensive, specialized tools and materials while they are in transit to a mountain job site. In Colorado, it is also vital to consider the specific environments in which you work. If your trade involves high-risk activities like roofing or electrical work in wildfire-prone zones, your Artisan Contractor Insurance must explicitly account for those environmental liabilities. Evaluating your specific daily tasks ensures you aren’t paying for fluff you don’t need while being fully shielded against the risks you actually face.

Comparing Providers, Policies, and Costs

Once you understand your specific needs, the next step is navigating the competitive Colorado insurance landscape. Cost is always a factor, but the cheapest premium often comes with high deductibles or restrictive exclusions that can cripple a small business during a claim.

When comparing providers, look for those who specialize in the construction industry. These providers often offer bundled packages, such as a Business Owner’s Policy (BOP), which combines general liability with property insurance at a discounted rate. Pay close attention to the “per-occurrence” vs. “aggregate” limits to ensure they meet the requirements of the general contractors or municipalities you contract with. You must also consider the provider’s reputation for claims handling in the Centennial State. A local agent who understands Colorado’s specific legal and climate challenges can be an invaluable advocate when you need to get back to work quickly.

You’ve spent years mastering your craft; don’t let one unforeseen accident take it all away. By choosing the right Artisan Contractor Insurance coverage today, you can focus on what you do best: building and beautifying Colorado. Consult with Prince Insurance today, and let’s make sure your trade is protected for the long haul!